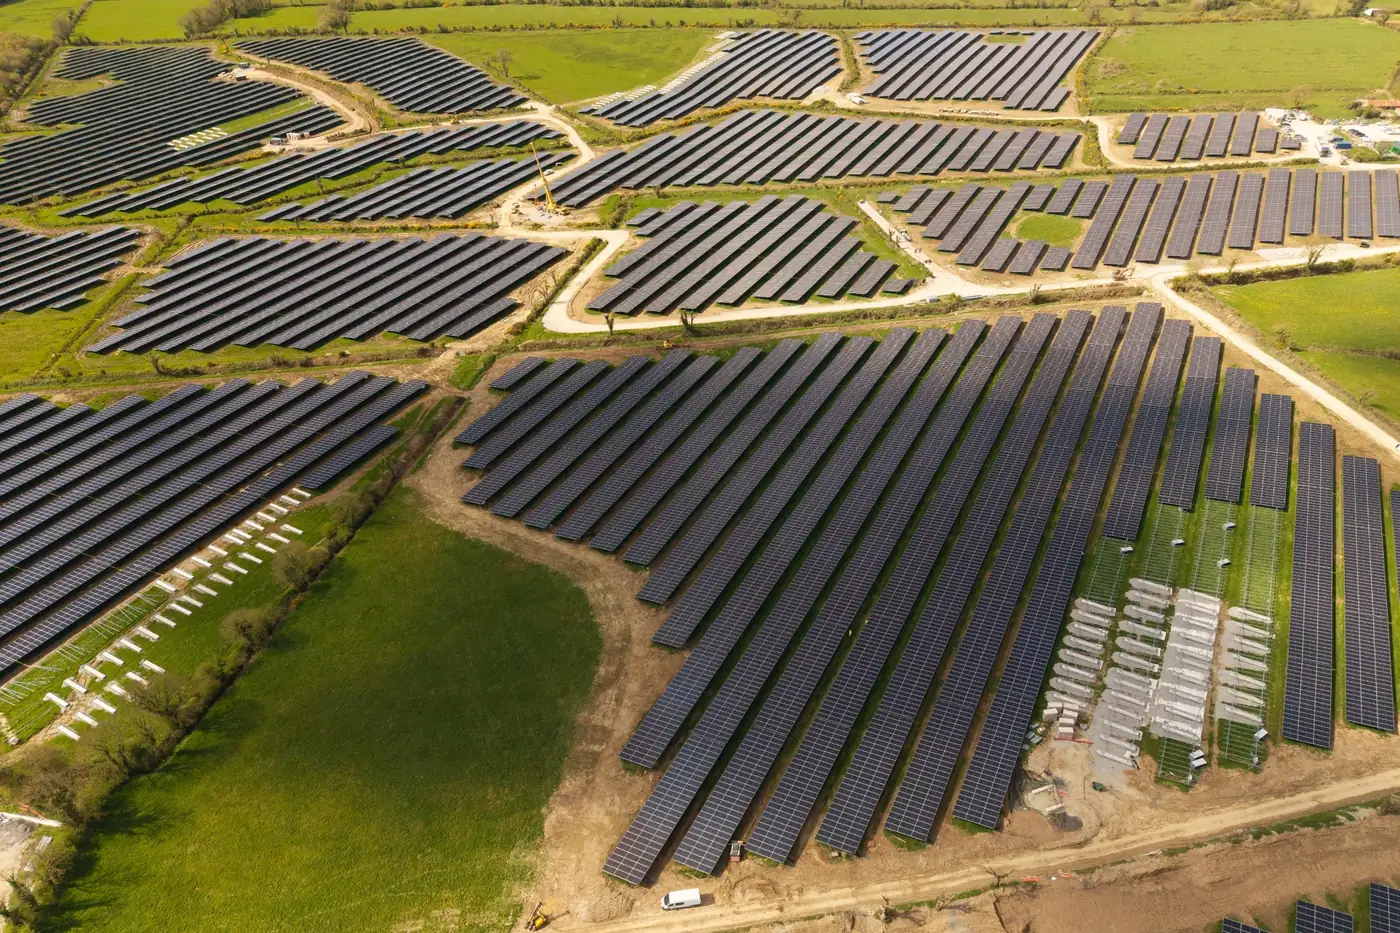
Green innovation in the UK is accelerating. Last year, the Intellectual Property Office received a record 785 requests through its Green Channel, its fast-track sustainable innovations route, up almost 40% on the year before.[1] Within Infratech, Greentech now accounts for the largest share of innovation activity among Murphy Capital’s three main investment verticals, as well as attracting the most equity funding in recent years.
Where the innovation is concentrated
Murphy Capital’s recently published report UK Infratech: From Innovation to Scale found that half of all Infratech spinouts and 41.2% of patenting companies sit within the Greentech vertical. That combination points to a deep and active research base producing a robust pipeline of new IP likely to keep coming through in the years ahead.
Within all three verticals, Energy and Digital & AI-related businesses lead the way in these innovation metrics, a reminder that sustainability-focused Infratech now depends as much on data, software and computational tools as it does on physical hardware or materials science.
This innovation sits alongside a supportive policy backdrop. Decarbonisation targets, together with initiatives such as Cleantech for UK,[2] and the government’s newly introduced Cleantech Innovation Challenges,[3] which support the commercialisation of early-stage intellectual property, have created conditions in which climate-focused ideas can move from the lab into investable businesses more readily than in many other parts of Infratech.
Greentech also benefits from sitting within multiple of the government’s eight Modern Industrial Strategy priority sectors, including Clean Energy Industries, Advanced Manufacturing and Digital and Technologies.[4] This breadth provides a structural advantage for Greentech businesses, allowing access to a range of targeted sectoral initiatives to translate innovation into commercial success.
A strong research base today feeds a pipeline of investable technology tomorrow. Combined with extensive policy support, the conditions look set to keep converting Greentech’s research strength into investable businesses over the next several years.
But policy support alone doesn’t guarantee a founder’s timeline matches an investor’s. In the years to come, bridging this gap is likely to prove crucial for Greentech founders.
From research to revenue
Research-led businesses often face a different kind of funding challenge to most start-ups. Deep IP takes longer to develop, longer to protect and longer to turn into a commercial product, timelines that can sit awkwardly with investors looking for a faster return.
Recent research from UKRI has found that spinouts face more difficulties than other start-ups in matching funder expectations.[5] A university spinout may have cutting-edge technology behind it, but still need time to build the commercial track record that conventional funding rounds are built around.
The scale of the problem is only going to grow. Greentech’s spinout and patent lead is still working its way through the pipeline, meaning more businesses in the years ahead will reach a stage where they are technically capable but not yet fully commercially proven.
Closing the gap between research and commercial success will increasingly depend on capital models built around longer research timelines rather than standard funding cycles, and on investors willing to look past conventional growth metrics alone.
It’s a shift Murphy Capital has built its own Greentech approach around, backing founders with real IP and university links behind them on a timeline that matches how long true innovation takes to mature.[6] Our patient capital approach recognises that technical validation and customer adoption do not always follow a conventional venture timetable. By aligning investment expectations with those realities, we give founders the flexibility to pursue ambitious growth without forcing commercial decisions around a predetermined exit date. As that pipeline grows, this combination of patience and technical depth is likely to define which businesses make it to scale.
[1] Intellectual Property Office, 2026. “Facts and figures: patents, trade marks, designs and hearings: 2025” (Accessed: September 2026).
[2] Cleantech for UK, 2026. “Cleantech for UK”. (Accessed: September 2026).
[3] Department for Energy Security and Net Zero, 2026. UK cleantech innovation challenges: programme overview”. (Accessed: September 2026).
[4] UK Government, 2025. “Clean Energy Industries Sector Plan”. (Accessed: September 2026).
[5] UKRI, 2026. “Deepening University-Investor Links”. (Accessed: September 2026).
[6] Murphy Capital, 2026. “Strategy”. (Accessed: September 2026).